






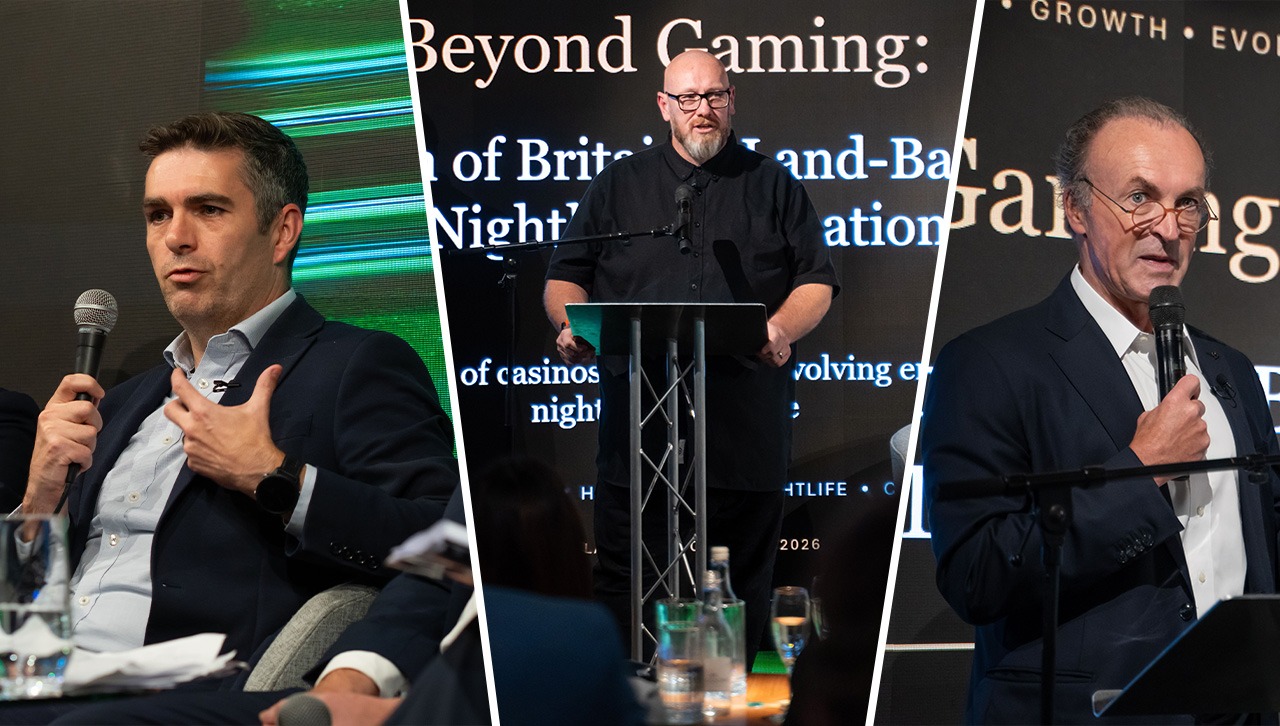
Nestled in Paddy Power sportsbook at the Hippodrome Casino, key stakeholders from the UK’s land-based sector gathered in the wake of the Night-Time Industries Association’s (NTIA) recent study into casinos at the intersect of the UK’s nightlife industry.
Hippodrome Casino Executive Chairman Simon Thomas’ opening remarks welcomed attendees by overviewing the future of the nation’s casinos and their role in the UK’s hospitality sector.
Indeed, he began by outlining that one third of the Hippodrome’s customers don’t gamble – illustrating the broader point that the casino industry does not necessarily revolve around gambling. This theme remained present throughout the afternoon, which saw key innovators from across retail rally behind the sector at a pivotal moment before the UK’s Autumn Budget and looming tax levies set for implementation in April 2027.
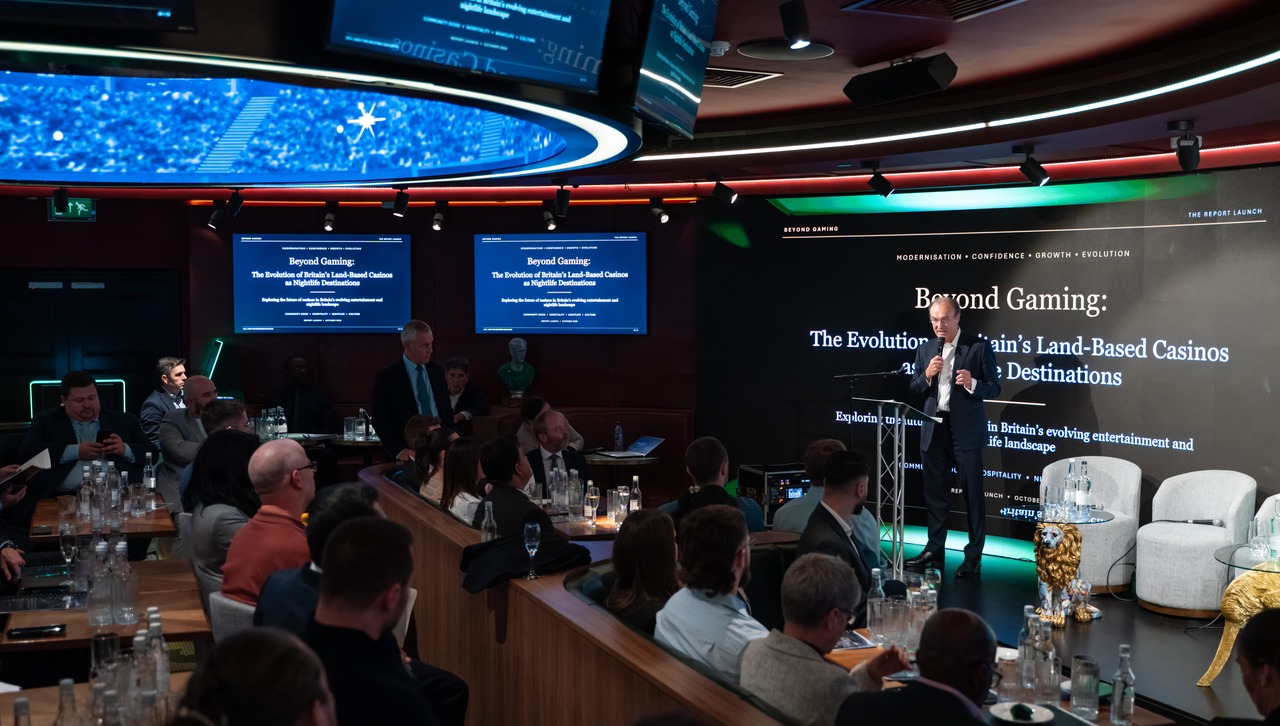
UK casinos: Much more than gaming...
Taking over from Thomas for the afternoon’s keynote presentation NTIA CEO Michael Kill began by broadly stating that when the industry discusses casinos, the conversation usually centres around gambling: “But that only tells part of the story.”
As a representative of the UK’s nightlife industry, Kill overviews that the central message of the NTIA’s most recent study highlights UK casinos’ role within the nation’s economy as “so much more than gambling.”
Kill highlights the community element that casinos provide, as he explained that the NTIA’s survey found the majority of participants agreed that they contribute positively to society. Economic contributions were also keenly pointed out, with the survey detailing that the average total spend on a UK casino visit was £204.50 ($271.06), whereas average night-out spend outside of casino properties was £86.80.
It’s not just about the property itself, they represent a catalyst for local economic growth
Indeed, Kill pointed out that, when surveying casino activity, the NTIA found that 53% dined at a casino on their most recent visit, 67% used the bar and 26% had visited because the casino was the only late-night option. These statistics were further used to highlight the non-gaming societal contributions that casinos make to the UK economy.
Importantly, however, Kill also outlined that a number of survey respondents visited casinos as they felt they were a safe late-night option in comparison to other alternatives. Further, with the average casino sector career span lasting 12.8 years, the long-term viability of the industry as a progressive career option was also strongly certified as part of the NTIA report.
Moving to the crux of the report, he discusses the knock-on effect of rising taxes, showing deep-rooted concern across a number of properties, with 95.7% expecting to reduce staff numbers and 91.3% expecting lower investment.
No safety without certainty
Of course, the UK casino industry currently exists within a realm of extreme uncertainty. As the afternoon’s panel presenters – NTIA CEO Michael Kill, Rank Group CEO Richard Harris, Genting Casino UK CEO Paul Willcock and Regulus Partners Partner Dan Waugh – take to the stage, Waugh opens by reiterating the sentiment of the NTIA’s report... “more than just gaming.”
Indeed, he reflects on an American Gaming Association (AGA) paper entitled Beyond the Gaming Floor, which claims that the true value of casinos is around 3/4x their gaming revenues, stating: “It’s not just about the property itself, they represent a catalyst for local economic growth.”
Uncertainty – arguably the word of the day – was referenced heavily by each panellist, individually, with a lack of intel on the upcoming UK Autumn Budget remaining a key point of contention. However, Kill emphasises how much UK Prime Minister Andrew Burnham emphasises the importance of the UK high street – and states that there is a huge importance in feeding the lifeblood of the casino industry.
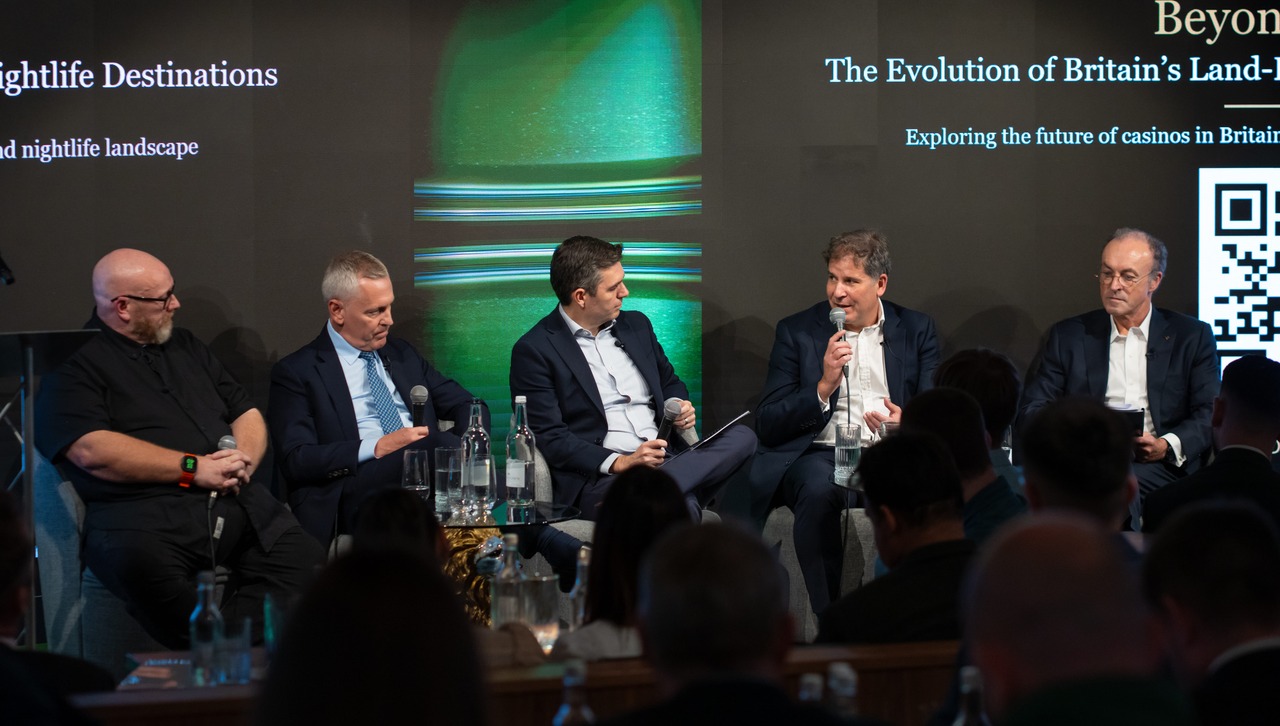
Sentimentally, then, the UK’s new PM should in essence display unwavering support of the UK’s casino industry, agreed the panel, given its vast contributions to the UK high-street economy. Nevertheless, with taxes already set to skyrocket in April 2027, and potential rises in Machine Game Duty on the way, the panel also takes its opportunity to highlight the difficulty of investment under stringent financial conditions.
Willcock explains: “Overseas industry organisations are itching to invest in the UK, they really are. But there needs to be more certainty.”
Continuing, he discusses upcoming investment and expansion plans at Genting, citing the approval of the Trocadero Casino (estimated to open in London’s West End in late 2027) as an investment opportunity he is “incredibly excited about, but if I were urged to make the decision to greenlight the project again today, it might be a different outcome.” He continues that casinos aren’t looking for a ‘free ride,’ they just want a regime that feels fair: “The 28 October date is looming ominously, and at risk of sounding like a broken record – there really is simply a lack of certainty.”
Thomas poses a final question to each of the panellists, individually: Looking ahead, what is the single most important change to unlock progression in Britain’s casino sector?
Willcock’s response: Taxation. Harris’ response: Allowing people to enjoy the entertainment element of the sector. For Waugh, it’s challenging the public health misperceptions that are causing difficulties for the industry. Kill states that, in his opinion, the value proposition is very important: Whether it’s the value of land-based casinos or the consumer, “we need to narrow in on where those values sit.”
What does this all mean for the sector?
Broadly, what the NTIA’s study and this panel presentation sought to implore is the fact that modernisation is the first step towards an industry flourishing – and a more supportive tax regime would be required to spark the investment required.
These financial pressures are well-established as a growth threat for the UK’s gambling industry, and many stakeholders will be hoping for – at the very least – an omission of additional tax rises in this year’s Autumn Budget.
Overseas industry organisations are itching to invest in the UK, they really are. But there needs to be more certainty
Of course, it is not just the casino industry that is treading challenging waters in the UK, as numerous sports betting operators have already announced hundreds of shop closures and thousands of layoffs in the nation after remote gaming duty rose from 21% to 40% this April, with sports betting duty also set to rise to 25% in April 2027.
However, these issues – tangible and significant as they are – may simply be symptomatic of a much wider problem, and that is; the UK industry is losing the public perception battle.
It’s no secret that gambling has been viewed as something of a scapegoat under the latest Labour regime. The public supports taxation on the industry, broadly, because it doesn’t yield a widely positive reputation and can generate eye-watering amounts of tax revenue due to its vast popularity. This leaves the industry in desperate need of a fresh approach to help highlight the positive economic and social contributions that it can make.
The retail sector is, evidently, becoming increasingly aware of this. Despite the panellists choosing to highlight the challenges befalling the industry from a financial standpoint, the overall sentiment of the afternoon drew on a celebration of what Britain’s casinos can offer beyond gaming. This is a sentiment that the rest of the industry could do with echoing at a time of uncertainty.
Rather than attempting to fight anti-gambling fire with pro-gambling fire. It’s time to be tactical...
According to Simon Thomas, the Hippodrome Casino contains more security cameras than Westminster – a fact that was outlined when discussing the importance of safety in casinos and the security of patrons